As the 30 September 2026 deadline for obtaining the tax audit report for FY 2025-26 (AY 2026-27) approaches, finance teams and auditors are closing the books and reconciling the figures that will go into Form 3CD. This is when discrepancies often surface: a TDS entry that does not tie back to Form 26AS, a creditor balance that does not match the vendor records, or stock figures that differ from the physical count.
Most of these issues are avoidable when identified early. A discrepancy found in September can usually be investigated and corrected with time to spare; the same issue discovered just before filing can lead to rushed adjustments or remain unresolved. The deadline stated here is the general deadline currently applicable to this tax-audit cycle and may be extended or otherwise changed by government notification.
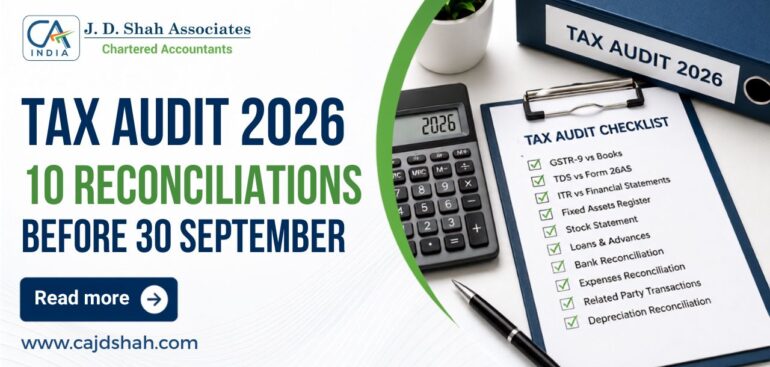
The ten reconciliations below are arranged in the sequence we recommend before finalising a tax audit report under Section 44AB. Some can be completed within a few hours; others may take longer where records have not been maintained consistently. Completing them well before the applicable deadline will make the audit process considerably smoother.
1. Bank Statements vs Books of Accounts
Start here, because everything else builds on it. Pull the 12-month bank statement for every current and savings account the business uses and match it line by line against the cash book. Look out for entries the bank shows that never made it into the books, bank charges, interest credited, cheques that bounced, standing instructions nobody remembered to record.
If there’s a business with more than two or three accounts, don’t do this manually. Use the bank statement import in your accounting software and let it flag the unmatched entries for you.
2. Turnover as per GST Returns vs Turnover as per Books
This is the one that gets the most notices. Add up the taxable value across all your GSTR-1 and GSTR-3B filings for the year and compare it to the sales figure in your books. They should match, or you should be able to explain the gap in one line.
Common reasons for a mismatch:
- Sales recorded in the books before the invoice was raised, or the other way around
- Advances that were taxed under GST but not yet booked as revenue
- Export sales or exempt supplies treated differently in the two records
- Credit notes issued after the GST return was filed
Clause 44 of the applicable Form 3CD requires a breakup of total expenditure between entities registered and not registered under GST. Check the notified form and instructions for the relevant assessment year, but do not leave this reconciliation until the end.
3. TDS Deducted vs 26AS, AIS/TIS and TDS Records
For TDS deducted from your income, download the latest Form 26AS and review AIS/TIS and the relevant Form 16 or Form 16A, as applicable. For TDS deducted by your business, reconcile the books with your TDS returns, challans, certificates, and TRACES reports, including any available justification report. Two things usually go wrong: the deductor has not deposited or correctly reported the TDS, so it is not showing up yet, or the books record a different amount from the amount actually deducted.
Do this for both sides: TDS deducted by others on your income, and TDS deducted by you on payments to vendors and employees. A mismatch on either side can delay a credit or refund or trigger a short-deduction or reporting query.
Tip: run this reconciliation quarterly through the year instead of once in September. It’s a much smaller job that way.
4. Fixed Assets Register vs Depreciation Claimed
Go through the fixed asset register and check that every addition and disposal during the year is actually reflected there, with the right date of purchase or sale. The date matters a lot for depreciation, since an asset used for less than 180 days only gets half the normal rate.
- Confirm additions have proper invoices and are capitalised correctly, not expensed
- Confirm assets sold or scrapped during the year have been removed from the register
- Check that depreciation as per the Income Tax Act (for the audit) and as per books (for accounting) are tracked separately, since the rates and methods differ
5. Physical Stock vs Books Stock
If the business carries inventory, arrange a physical count close to year-end and reconcile the physical quantity and valuation with the books. Material differences should be investigated, documented, and adjusted where appropriate, rather than ignored.
Also check the valuation method itself. If you’ve been valuing stock at cost in some years and at cost-or-market-value-whichever-is-lower in others, that inconsistency will get flagged.
6. Sundry Debtors and Creditors Confirmation
Send balance confirmation requests to your major debtors and creditors, and reconcile any differences before the audit. This protects you two ways. It confirms the year-end balances are genuine, and it gives you early warning of debts that are unlikely to be recovered, which matters for provisioning.
- Reconcile advances given or received that are sitting unadjusted for a long time
- Check for old balances that should have been written off but are still on the books
- Flag any related party balances separately, since they need extra disclosure
7. Statutory Dues: PF, ESI, GST, and TDS Payment Timelines
Clause 26 and the relevant disallowance provisions under Sections 36(1)(va) and 43B make the timing of statutory payments important. Pull the payment challans for PF, ESI, professional tax, GST, and TDS and match each payment date against the applicable due date. Employee contributions to PF or ESI are governed by Section 36(1)(va) and the relevant statutory due dates; employer contributions are dealt with under Section 43B, subject to the applicable rules.
A late payment of an employee PF or ESI contribution may result in disallowance where it is not deposited by the relevant statutory due date. Do not assume that the treatment is the same as for the employer contribution, and verify the position applicable to the relevant assessment year.
8. Related Party Transactions vs Disclosures
List out every transaction with directors, partners, relatives, and group companies during the year, and check it against what’s already disclosed in the financial statements. Clause 23 of Form 3CD wants specific details of payments to persons covered under Section 40A(2)(b), so anything missed here becomes a direct query during the audit.
9. Loans and Advances: Mode of Acceptance and Repayment
Go through every loan, deposit, or specified sum taken or repaid during the year and check the mode of acceptance or repayment. Sections 269SS and 269T generally restrict cash transactions above the prescribed thresholds and may attract a penalty equal to the amount involved. Statutory exceptions apply, and the result depends on the nature of the transaction and the parties involved, so confirm the specific facts before concluding that a transaction is non-compliant.
- Check loans from directors, partners, and relatives, not just outside lenders
- Check the mode of repayment as carefully as the mode of receipt
- Confirm interest paid on these loans has had the right TDS applied
10. Prior Year’s Audit Observations and Carried Forward Figures
Before you close this year’s audit, go back to last year’s Form 3CD and tax computation. Confirm that carried forward losses, unabsorbed depreciation, and opening balances of debtors, creditors, and fixed assets all tie back exactly to what was reported last year.
This sounds obvious, but it’s the one people skip most often, and it’s usually where an assessing officer starts if a case gets picked up for scrutiny later.
Why Bother With All This Before the Deadline
None of these ten reconciliations are complicated on their own. What makes them hard is doing all of them in the last week of September, alongside everything else that’s due at the same time. A mismatch you catch in the second week of the month is a quick fix. The same mismatch found the night before filing turns into a rushed adjustment, or worse, gets filed anyway and shows up as a notice six months later.
Start this list now if you haven’t already. Give yourself time to chase confirmations, fix ledger entries, and actually think through the numbers instead of just closing them.
Final Thought
A tax audit report is only as good as the reconciliations behind it. Getting these ten right before the applicable 30 September 2026 deadline does not just support compliance; it makes the audit faster and less stressful for everyone involved, including your auditor.
If your books need cleanup before the deadline, or you want a second review of any of these reconciliations, speak with a qualified chartered accountant well before the filing date. J.D. Shah Associates helps businesses in Mumbai and Borivali with tax-audit preparation, GST reconciliation, and Form 3CD compliance.
Disclaimer: This article is for general information only and is not professional tax or legal advice. Applicability may vary based on the taxpayer’s facts and the rules applicable for the relevant assessment year. Consult a qualified chartered accountant before filing.